October 16, 2026
Postcard from Bangkok
Nerves are showing at the World Bank and IMF annual meetings
To the point!
"The dark clouds gathering overhead are impossible to miss, even in Bangkok."
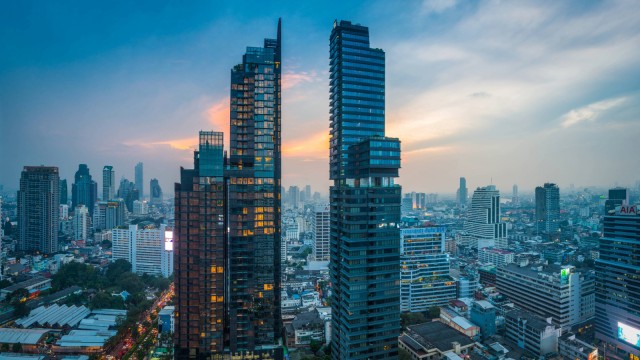
As they do every October, government officials, central bankers and other financial-sector figures are gathering for the annual meetings of the International Monetary Fund (IMF) and the World Bank. LBBW is here too, of course. This year’s gathering is in Bangkok, Thailand’s capital. Please don’t ask about the traffic. It’s beyond description. In conversations and panel discussions, everyone is trying to strike a somewhat upbeat note. And the global economy has indeed proved resilient despite geopolitical crises, trade disputes and rising inflation and interest rates. But the dark clouds gathering overhead are impossible to miss, even in Bangkok. In its closely watched, twice-yearly World Economic Outlook (WEO), the IMF has largely reaffirmed its April forecast for global growth: 3.1% this year and 3.4% in 2027. A closer reading, though, shows that the report dwells above all on the risks to that outlook. Those concerns have also come up in discussions here to which I’ve had the chance to contribute.
Public finances under pressure
IMF, the joke goes, stands for “it’s mostly fiscal”. The quip harks back to the conditions the fund attaches to support for developing countries facing balance-of-payments trouble. A regular condition for releasing loan tranches is that governments shore up their budgets to curb excess demand. The latest WEO, too, contains plenty of warnings about unsustainable fiscal policy. This time, however, most concern advanced economies. A prolonged conflict in the Middle East, in particular, could bring further bursts of inflation, potentially prompting central banks to raise rates again. That would add to the already rising interest burden of heavily indebted advanced economies and deepen doubts about the sustainability of their public finances. Adverse feedback loops could push rates higher still, increasing the fiscal strain. Many countries are also choosing ill-suited ways to shield people from rising energy prices – Germany’s measures to curb fuel prices spring to mind – adding to debt and deficits.
Accordingly, the IMF has nudged up its forecast for the G7’s debt-to-GDP ratio in 2031, from 133% in April to 135%. Germany’s ratio is currently 65% and is projected by the IMF to reach 76% by 2031. That leaves it in relatively sound shape by comparison – though that is hardly a high bar. Even so, the IMF has been telling delegates at every opportunity that downside risks predominate. After decades spent analyzing public finances, I agree. Governments seem to be hoping that central banks will once again come to the rescue. But central banks can, at best, buy time. The hard work falls to governments. They need to use the time that central banks can buy them by consolidating the out-of-shape budgets.
An unbalanced global economy
Another recurring theme is how heavily global economic momentum depends on investment in artificial intelligence. U.S. growth, for example, rests to a considerable extent on building data centers and related infrastructure, while investment elsewhere in the economy is weaker than in 2025. Growth is becoming concentrated in ever fewer countries (see Figure).
Fig.: Number of countries accounting for 95% of global economic growth
The IMF points to winners and losers among countries, with growth rates diverging further. Poorer countries in particular are at risk of falling behind. They don’t benefit from the AI boom but have to bear the brunt of a higher import bill for fossil fuels as a consequence of the Iran war and higher food import prices as a result of fewer shipments arriving from the Black Sea due to the fact that Russia is threatening Ukrainian ships carrying wheat and other grains.
The IMF’s Global Financial Stability Report also highlights risks to financial stability. At the heart of its concern is how AI investment is financed. The fund regards circular deals as particularly risky: hyperscalers are putting some $300 billion into financially weaker and often profitless AI firms. There is also $650 billion in debt as investments can no longer be financed through free cash flow. In return, the recipients have committed to $1.4 trillion in future spending, for instance on computing power or chips. These interlocking arrangements make financial flows harder to trace – especially if more such deals remain undisclosed.
Finally, the IMF’s managing director, Kristalina Georgieva, has publicly warned of a slow-motion tsunami for jobs and tax revenues from AI. That is likely to hamper economic development and deepen social divisions. In a nutshell, the mood in Bangkok is decidedly somber. While all recognize the resilience of the world economy, the fear is that crunch time is drawing closer.
Dr. Moritz Kraemer, Chief Economist / Head of Research at LBBW
Download To the point!
-
1.2 MB | October 16, 2026
This publication is addressed exclusively at recipients in the EU, Switzerland, Liechtenstein and the United Kingdom.
This report is not being distributed by LBBW to any person in the United States and LBBW does not intend to solicit any person in the United States.
LBBW is under the supervision of the European Central Bank (ECB), Sonnemannstraße 22, 60314 Frankfurt/Main (Germany) and the German Federal Financial Supervisory Authority (BaFin), Graurhein-dorfer Str. 108, 53117 Bonn (Germany) / Marie-Curie-Str. 24-28, 60439 Frankfurt/Main (Germany).
This publication is based on generally available sources which we are not able to verify but which we believe to be reliable. Nevertheless, we assume no liability for the accuracy and completeness of this publication. It conveys our non-binding opinion of the market and the products at the time of the editorial deadline, irrespective of any own holdings in these products. This publication does not replace individual advice. It serves only for informational purposes and should not be seen as an offer or request for a purchase or sale. For additional, more timely in-formation on concrete investment options and for indi-vidual investment advice, please contact your investment advisor.
We retain the right to change the opinions expressed herein at any time and without prior notice. More-over, we retain the right not to update this information or to stop such updates entirely without prior notice.
Past performance, simulations and forecasts shown or described in this publication do not constitute a reliable indicator of future performance.
The acceptance of provided research services by a securities services company can qualify as a benefit in supervisory law terms. In these cases LBBW assumes that the benefit is intended to improve the quality of the relevant service for the customer of the benefit recipient.
Additional Disclaimer for recipients in the United Kingdom:
Authorised and regulated by the European Central Bank (ECB), Sonnemannstraße 22, 60314 Frank-furt/Main (Germany) and the German Federal Financial Supervisory Authority (BaFin), Graurheindorfer Str. 108, 53117 Bonn (Germany) / Marie-Curie-Str. 24-28, 60439 Frankfurt/Main (Germany). Authorised by the Prudential Regulation Authority. Subject to regulation by the Financial Conduct Authority and limited regulation by the Prudential Regulation Authority. Details about the extent of our regulation by the Prudential Regulation Authority are available from us on request.
This publication is distributed by LBBW to professional clients and eligible counterparties only and not retail clients. For these purposes, a retail client means a person who is one (or more) of (i) a client as defined in point (7) of Article 2(1) of the UK version of Regulation (EU) 600/2014 which is part of UK law (UK MiFIR) by virtue of the European Union (Withdrawal) Act 2018 (EUWA) who is not a professional client (as defined in point (8) of Article 2(1) of UK MiFIR); or (ii) a customer within the meaning of the provisions of the Financial Services and Markets Act 2000 (as amended, the FSMA) and any rules or regulations made under the FSMA (which were relied on immediately before the 31 December 2020 (IP completion day)) to implement Directive (EU) 2016/97 on insurance distribution, where that customer would not qualify as a professional client, as defined in point (8) of Article 2(1) of UK MiFIR; or (iii) not a qualified investor as defined in the UK version of Regulation (EU) 2017/1129 on the prospectus to be published when securities are offered to the public or admitted to trading on a regulated market, which is part of UK law by virtue of the EUWA (the UK Prospectus Regulation).
This publication has been prepared by LBBW for information purposes only. It reflects LBBW’s views and it does not offer an objective or independent outlook on the matters discussed. The publication and the views expressed herein do not constitute a personal recommendation or investment advice and should not be relied on to make an investment decision. The appropriateness of a particular investment or strategy will depend on an investor’s individual. You should make your own independent evaluation of the relevance and adequacy of the information contained in this publication and make such other investigations as you deem necessary, including obtaining independent financial advice, before partici-pating in any transaction in respect of the financial instruments referred to this publication herein.
Under no circumstance is the information contained within such publication to be used or considered as an offer to sell or a solicitation of an offer to buy any particular investment or security. Neither LBBW nor any of its subsidiary undertakings or affiliates, directors, officers, employees, advisers or agents accepts any responsibility or liability whatsoever for/or makes any representation or warranty, express or implied, as to the truth, fullness, accuracy or completeness of the information in this publication (or whether any information has been omitted from the publication) or any other information relating to the, whether written, oral or in a visual or electronic form, and howsoever transmitted or made available or for any loss howsoever arising from any use of this publication or its contents or otherwise arising in connection therewith.
The information, statements and opinions contained in this publication do not constitute or form part of a public offer. LBBW assumes no responsibility for any fact, recommendation, opinion or advice con-tained in any such publication and expressly disclaims any responsibility for any decisions or for the suitability of any security or transaction based on it. Any decisions that a professional client or eligible counterparty may make to buy, sell or hold a security based on such publication will be entirely their own and not in any way deemed to be endorsed or influenced by or attributed to LBBW.
LBBW does not provide investment, tax or legal advice. Prior to entering into any proposed transaction on the basis of the information contained in this publication, recipients should determine, in consultation with their own investment, legal, tax, regulatory and accounting advisors, the economic risks and merits, as well as the legal, tax, regulatory and accounting characteristics and consequences, of the transac-tion.