October 02, 2026
Postcard from Naples
Italy has become a haven of political stability. No joke!
To the point!
"Prejudices travel light. Alas, reality is often more nuanced – but sometimes rather more pleasing, too."
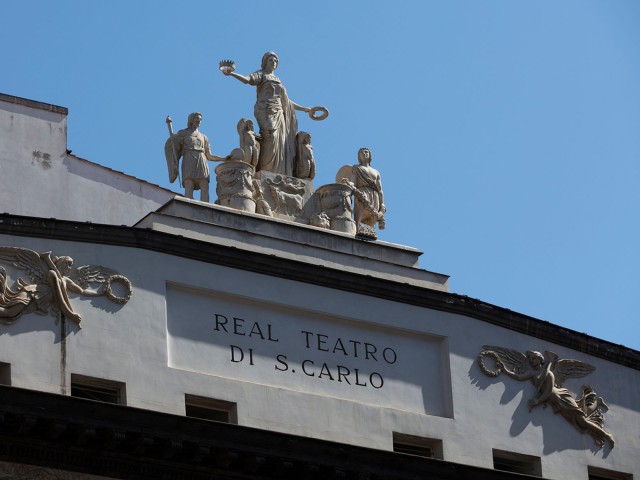
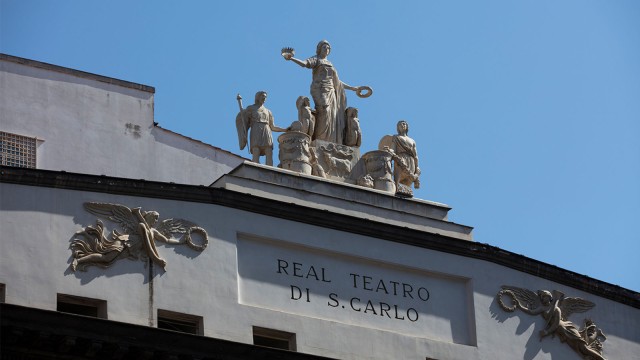
Some of you may have been waiting for my postcard from the summer vacation. Here it is! A week sailing on the Mediterranean, followed by a few days in Naples. The trip included the magnificent Teatro San Carlo (see photo), the world’s oldest continuously operating opera house. Milan’s La Scala pales by comparison – not least in the enthusiasm of its audience.
Italy has changed – for the better
So, Italy. I remember a time when prime ministers changed so often that learning their names scarcely seemed worthwhile. Between 1968 and 2022, Italy had no fewer than 32 heads of government. Only a handful stayed at the helm for more than two years: Craxi, Andreotti, Prodi, Berlusconi, Renzi and Conte. Technocratic prime ministers, such as Mario Draghi, previously the president of the European Central Bank, often took office; many others were brought down by party intrigue.
That has changed. Giorgia Meloni, Italy’s first woman prime minister and leader of the right-wing nationalist Fratelli d’Italia party, will have been in office for four years in October. No government since Mussolini’s has remained in power uninterrupted for longer. France and Britain now change prime ministers with the frequency once familiar in il Bel Paese. And the revolving door of Italian prime ministers is not the only thing to have slowed down, at least for now. Italian economic policy, too, has become comparatively predictable (see fig. 1). Germany could take a leaf out of Italy’s book, as could Paris and London. That does not, of course, mean Italian politics is successful. After all, Italy’s GDP per capita has dropped from around 120% of the EU average at the turn of the century to just over 90% now. Even so, policies are less defined by uncertainty than Germany’s.
Fig. 1: Economic Policy Uncertainty Index
through July 2026
⬤ {series.name}: {point.y}
Tax evasion: a national sport?
Naturally, Naples conjures images of organized crime. The Camorra, Campania’s mafia syndicate, is well known in the rest of the world, too. Recorded crime is indeed higher than, say, in Berlin, though it has recently risen faster there. As a tourist, however, I saw none of it. Had I been running a pizzeria, I might have had a rather different experience – and attracted some unwelcome visitors trying to extract some protection money.
Many of you will also assume that tax evasion remains a national sport in Italy. But beware. Tax evasion is, by definition, difficult to measure. Still, various studies compare its different facets internationally. Fig. 2 shows how misleading such assumptions can be. Germans have, in fact, shifted more money into tax havens than Italians.
Fig. 2: Offshore Wealth by country of origin
% of GDP
Public finances steadier than usual
And now, brace yourselves: for this year and 2027, the European Commission expects Germany’s budget deficit, as a share of GDP, to be larger than Italy’s – the perennial fiscal sinner (see fig. 4). Whether that comes to pass remains to be seen. Even if Germany’s deficit does prove higher, Italy’s success is not solely the product of its own reforming zeal.
Fig. 4: Shadow economy 2026
% of GDP
The country benefits more than any other EU member state from the blessings of the NextGenerationEU program – jointly issued debt intended to repair the economic damage inflicted by the COVID-19 pandemic. Roughly one-third takes the form of grants from Brussels, which recipient states may book directly as revenue. That flatters Italy’s fiscal figures and makes them look better than they otherwise would. Bella figura!
Nor must we discard every cherished stereotype. Italy remains a leader in undeclared work. The shadow economy is estimated to account for over 20% of GDP, well ahead of European peers bar Greece (see fig. 3).
Fig. 3: General government deficit
% of GDP
The old narrative no longer holds
Lest this create the wrong impression: Italy is by no means a model of fiscal virtue. Public debt between the Brenner Pass and Sicily remains enormous, productivity weak and demographic trends even less encouraging than in Germany. Yet the familiar tale of a chronically chaotic Bel Paese is becoming ever less convincing. Italy has gained political stability, has its public finances – at least for the time being – better under control, and has eased some of its notorious weaknesses.
Germany, by contrast, is heading in the wrong direction. It cannot rely on its southern neighbor kindly playing the role of economic-policy problem child forever. Perhaps that is the real postcard from Naples: prejudices travel light. Alas, reality is often more nuanced – but sometimes rather more pleasing, too.
Dr. Moritz Kraemer, Chief Economist / Head of Research at LBBW
Download To the point!
-
413.2 KB | October 02, 2026
This publication is addressed exclusively at recipients in the EU, Switzerland, Liechtenstein and the United Kingdom.
This report is not being distributed by LBBW to any person in the United States and LBBW does not intend to solicit any person in the United States.
LBBW is under the supervision of the European Central Bank (ECB), Sonnemannstraße 22, 60314 Frankfurt/Main (Germany) and the German Federal Financial Supervisory Authority (BaFin), Graurhein-dorfer Str. 108, 53117 Bonn (Germany) / Marie-Curie-Str. 24-28, 60439 Frankfurt/Main (Germany).
This publication is based on generally available sources which we are not able to verify but which we believe to be reliable. Nevertheless, we assume no liability for the accuracy and completeness of this publication. It conveys our non-binding opinion of the market and the products at the time of the editorial deadline, irrespective of any own holdings in these products. This publication does not replace individual advice. It serves only for informational purposes and should not be seen as an offer or request for a purchase or sale. For additional, more timely in-formation on concrete investment options and for indi-vidual investment advice, please contact your investment advisor.
We retain the right to change the opinions expressed herein at any time and without prior notice. More-over, we retain the right not to update this information or to stop such updates entirely without prior notice.
Past performance, simulations and forecasts shown or described in this publication do not constitute a reliable indicator of future performance.
The acceptance of provided research services by a securities services company can qualify as a benefit in supervisory law terms. In these cases LBBW assumes that the benefit is intended to improve the quality of the relevant service for the customer of the benefit recipient.
Additional Disclaimer for recipients in the United Kingdom:
Authorised and regulated by the European Central Bank (ECB), Sonnemannstraße 22, 60314 Frank-furt/Main (Germany) and the German Federal Financial Supervisory Authority (BaFin), Graurheindorfer Str. 108, 53117 Bonn (Germany) / Marie-Curie-Str. 24-28, 60439 Frankfurt/Main (Germany). Authorised by the Prudential Regulation Authority. Subject to regulation by the Financial Conduct Authority and limited regulation by the Prudential Regulation Authority. Details about the extent of our regulation by the Prudential Regulation Authority are available from us on request.
This publication is distributed by LBBW to professional clients and eligible counterparties only and not retail clients. For these purposes, a retail client means a person who is one (or more) of (i) a client as defined in point (7) of Article 2(1) of the UK version of Regulation (EU) 600/2014 which is part of UK law (UK MiFIR) by virtue of the European Union (Withdrawal) Act 2018 (EUWA) who is not a professional client (as defined in point (8) of Article 2(1) of UK MiFIR); or (ii) a customer within the meaning of the provisions of the Financial Services and Markets Act 2000 (as amended, the FSMA) and any rules or regulations made under the FSMA (which were relied on immediately before the 31 December 2020 (IP completion day)) to implement Directive (EU) 2016/97 on insurance distribution, where that customer would not qualify as a professional client, as defined in point (8) of Article 2(1) of UK MiFIR; or (iii) not a qualified investor as defined in the UK version of Regulation (EU) 2017/1129 on the prospectus to be published when securities are offered to the public or admitted to trading on a regulated market, which is part of UK law by virtue of the EUWA (the UK Prospectus Regulation).
This publication has been prepared by LBBW for information purposes only. It reflects LBBW’s views and it does not offer an objective or independent outlook on the matters discussed. The publication and the views expressed herein do not constitute a personal recommendation or investment advice and should not be relied on to make an investment decision. The appropriateness of a particular investment or strategy will depend on an investor’s individual. You should make your own independent evaluation of the relevance and adequacy of the information contained in this publication and make such other investigations as you deem necessary, including obtaining independent financial advice, before partici-pating in any transaction in respect of the financial instruments referred to this publication herein.
Under no circumstance is the information contained within such publication to be used or considered as an offer to sell or a solicitation of an offer to buy any particular investment or security. Neither LBBW nor any of its subsidiary undertakings or affiliates, directors, officers, employees, advisers or agents accepts any responsibility or liability whatsoever for/or makes any representation or warranty, express or implied, as to the truth, fullness, accuracy or completeness of the information in this publication (or whether any information has been omitted from the publication) or any other information relating to the, whether written, oral or in a visual or electronic form, and howsoever transmitted or made available or for any loss howsoever arising from any use of this publication or its contents or otherwise arising in connection therewith.
The information, statements and opinions contained in this publication do not constitute or form part of a public offer. LBBW assumes no responsibility for any fact, recommendation, opinion or advice con-tained in any such publication and expressly disclaims any responsibility for any decisions or for the suitability of any security or transaction based on it. Any decisions that a professional client or eligible counterparty may make to buy, sell or hold a security based on such publication will be entirely their own and not in any way deemed to be endorsed or influenced by or attributed to LBBW.
LBBW does not provide investment, tax or legal advice. Prior to entering into any proposed transaction on the basis of the information contained in this publication, recipients should determine, in consultation with their own investment, legal, tax, regulatory and accounting advisors, the economic risks and merits, as well as the legal, tax, regulatory and accounting characteristics and consequences, of the transac-tion.